Car Loans Online Vehicle Lease Repayment Calculator
Explore potential car leasing costs with our Car Lease Calculator. Estimate monthly payments and test different interest rates, lease terms and residual (balloon) amounts to see how these variables may influence your repayments and overall leasing costs.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility assessments or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Car Lease Details:
Important!
Car Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Car Lease Amortisation Calculator
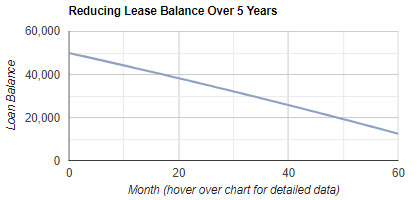
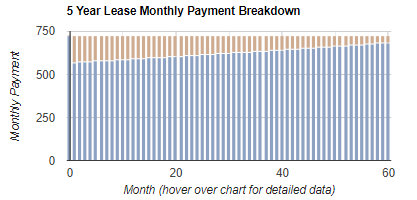
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Vehicle Lease Repayment Calculator
Our Vehicle Lease Repayment Calculator helps you estimate monthly lease repayments for a motor vehicle by modelling three key variables: interest rate, lease term, and the residual or balloon amount payable at the end. It’s important because small changes to any of these inputs can materially affect cash flow, total interest over the term, and the end-of-lease obligation, helping you compare scenarios before you speak with a lender or novated leasing provider.
How to complete the form for the best result:
1. Purchase Price
Enter the total amount you want financed for the vehicle. Include relevant upfront costs you intend to roll into the lease (for example, on-road costs or insurance where applicable). Use whole numbers only (no decimals, commas, or dots).
2. Balloon or Residual Value (percent of purchase price)
Select the residual percentage. A higher residual generally reduces the monthly payment but increases the amount left owing at the end, which can increase overall cost across the term. Choose a residual that matches your intended end-of-lease plan (keep, refinance, or sell).
3. Term of Loan (years)
Choose the number of years. Longer terms usually reduce monthly repayments but can increase total interest paid. Select a term that suits how long you expect to keep the vehicle and your budget tolerance.
4. Interest Rate (per annum)
Select an interest rate to simulate. Use a conservative rate when stress-testing affordability, because your actual rate may differ depending on lender policy and your circumstances.
5. Calculate
Click calculate to generate your estimated monthly lease repayment and amortisation visuals.
How to interpret the results:
1. Monthly repayment estimate: Use this as a budgeting guide and compare scenarios by adjusting term, rate, and residual.
2. Amortisation charts: Review how the balance reduces over time and how much of each payment is interest versus principal; this highlights when interest costs are highest and the impact of a larger residual.
ASIC compliance note: This guide is general information only and does not consider your objectives, financial situation or needs. Consider the full lease contract, fees, taxes, insurance, maintenance, and end-of-lease options before deciding, and consider getting personal advice if needed.
Owning a car comes with a lot of responsibilities and unexpected expenses. From regular maintenance to surprise repairs, the costs can quickly add up and create financial stress. - read more
The anticipation of buying your dream car can be both exhilarating and daunting. It's a milestone that signifies personal success, a reward for hard work, and the freedom to explore the open road in a car that you truly adore. However, acquiring that dream vehicle is not merely about making a wish and waiting for it to come true; it requires smart financial planning and strategic decision-making. - read more
Embarking on the journey to purchase a new car is an exhilarating experience, full of the promise of fresh adventures and the satisfaction of ownership. Yet, beneath the sheen and thrill, important financial decisions are at play, particularly when it comes to your car loan agreement. Understanding the importance of negotiating the terms of your car loan cannot be overstated, as a savvy deal can lead to significant savings over time. - read more
Car loan criteria are the standards lenders use to assess whether an applicant is likely to manage repayments. In Australia, these criteria commonly include credit history, income, employment stability, existing debts, the requested loan amount, any deposit and the vehicle being financed. - read more
Car loans can help Australians spread the cost of buying a vehicle, but the advertised interest rate is only one part of the total cost. Fees, add-ons, repayment conditions and end-of-term obligations can all affect how much a loan costs over time. - read more
Personal car loans and business car loans can both help Australians finance a vehicle, but they are assessed and structured differently. This guide explains how loan purpose, borrower type, vehicle use, documentation and tax considerations can affect the option you choose. - read more
Your credit score is one of the factors lenders use when assessing car finance. Understanding how it works can help you prepare, compare options more clearly and avoid focusing only on the monthly repayment. - read more
Australian car buyers have received a little more certainty, with the Reserve Bank of Australia keeping the official cash rate steady at its latest board meeting. For households, sole traders and small business owners considering a vehicle purchase, the decision reduces one source of short-term uncertainty. It does not, however, mean car finance has suddenly become simple or uniformly cheaper. - read more
Late-August car loan market reporting suggests Australian borrowers are still seeing pockets of sharp competition, particularly for newer vehicles and applicants with strong credit profiles. That is encouraging for households and small business owners who delayed a purchase during the winter, but it should not be read as a blanket sign that all finance has become cheaper or easier to secure. - read more
Australia’s electric vehicle story is moving beyond new-car sales and into the used-car yard. Latest industry reporting points to a softer second-hand EV market, with prices under pressure as more near-new electric cars reach resale channels and manufacturers keep discounting selected new models. For buyers, that can look like an opening: a lower purchase price may bring an EV within reach without stretching to a brand-new model. - read more
Australia’s New Vehicle Efficiency Standard has moved from policy debate into a practical market force for new-car buyers. The scheme is designed to push the national fleet towards lower-emission vehicles by setting targets for car makers across the vehicles they supply. It does not ban petrol or diesel models, but it does change the commercial pressure behind what arrives in showrooms, how it is priced and where incentives may appear. - read more
Australia’s new-car market has entered a very different phase, with June 2026 delivering the strongest monthly sales result on record and electric vehicles moving from niche consideration to mainstream choice. The latest figures show more than 140,000 new vehicles delivered across the month, with battery-electric models accounting for almost one in four sales. For car buyers, that is not just an automotive story. It is a finance story. - read more
Fresh July 2026 car loan comparison data points to a competitive market for well-qualified borrowers, with some secured car loan products advertising rates in the mid-five per cent range. For buyers looking at a new or near-new vehicle, that may sound encouraging after a period of higher household costs and tighter lending conditions. But the more useful takeaway is not simply that lower advertised rates exist. - read more
Australia’s new-car market has delivered another major signal to borrowers: the vehicle choices shaping car finance are changing quickly. In June 2026, combined new-vehicle deliveries reached 140,058, making it the strongest month recorded for the local market. The headline number matters, but the detail matters even more for buyers planning personal or business car loans. - read more